
Best No Annual Fee Credit Cards: Compare Fees, Rewards and Fit
Compare six cards with no annual card fee, including cash-back rates, quarterly caps, membership requirements and housing rewards.
A $0 annual fee removes one cost. Interest, transaction fees and any separate membership still matter. Start with a simple rewards option, then compare category cards against your normal spending. These six picks cover different uses; none guarantees approval or a better credit score.
By Alex Compton · Updated
Compare the cards at a glance
Annual fees come from our card records and are checked against this guide’s source review. Rewards shown are ongoing earning, not welcome bonuses. Conditions and exclusions apply.
| Card | Consider for | Annual fee | Ongoing rewards |
|---|---|---|---|
| Citi Double CashPersonal card | Flat-rate cash back | $0 | 2% on purchases: 1% when you buy and 1% as you pay. Total 5% on eligible hotels, car rentals and attractions booked through Citi Travel. |
| Chase Freedom UnlimitedPersonal card | Dining, drugstores and a flat base rate | $0 | 5% on Chase Travel purchases; 3% on dining and drugstores; 1.5% on other purchases. |
| U.S. Bank Cash+ Visa SignaturePersonal card | Categories you choose | $0 | 5% on the first $2,000 combined each quarter in two selected categories; 2% in one selected everyday category; 1% on other eligible purchases. |
| Discover it Cash BackPersonal card | Rotating quarterly categories | $0 | 5% in activated quarterly categories on up to $1,500 of purchases per quarter; 1% on other purchases. |
| Prime VisaPersonal card | Existing eligible Prime members | $0 | 5% at Amazon.com, Audible.com, Whole Foods Market and Chase Travel with eligible Prime membership; 2% on gas, dining and local transit; 1% otherwise. |
| Bilt Blue CardPersonal card | Housing rewards with spending conditions | $0 | 1x Bilt Points on other everyday purchases. Eligible housing payments can earn up to 1.25x under Housing-only rewards, depending on everyday spending. |
How we selected these cards
We compare six cards by ongoing rewards, annual card fee, caps, activation requirements, redemption rules and separate costs. The order groups use cases rather than declaring one universal winner. Fees and the stated reward conditions were checked against issuer sources on the dates shown. We do not claim a complete market survey or hands-on testing of every card. Guide checks do not renew welcome offers or full card reviews. Compensation does not determine these selections.
Our rating methodology and editorial policy
Citi Double Cash
Flat-rate cash back
Consider it when you want cash rewards without quarterly category selection. The second part of the base reward depends on payment; cash back is earned as ThankYou Points with cash redemption options.
Main tradeoff: Balance transfers do not earn rewards. A balance-transfer promotion does not automatically make new purchases interest-free.
Guide fee and rewards checked 2026-10-23. Full card review verified 2026-10-22.

Chase Freedom Unlimited
Dining, drugstores and a flat base rate
This can fit spending split between dining, drugstores and miscellaneous purchases. Compare the lower base rate with a flat 2% option using your actual category mix.
Main tradeoff: The 5% travel rate requires Chase Travel bookings. No annual fee does not rule out interest, transfer fees or other charges.
Guide fee and rewards checked 2026-10-23. Full card review verified 2026-11-02.

U.S. Bank Cash+ Visa Signature
Categories you choose
Consider it when recurring expenses fit the available categories, such as home utilities or cell phone providers. The 5% cap applies to the two categories together, not separately.
Main tradeoff: Choose and activate categories each quarter. Unselected categories and spending above the 5% cap generally earn 1%; merchant exclusions apply.
Guide fee and rewards checked 2026-10-23. Full card review verified 2026-11-02.

Discover it Cash Back
Rotating quarterly categories
This suits someone willing to follow a changing category calendar. Compare the categories with planned purchases rather than shifting spending just to earn a higher rate.
Main tradeoff: Activation and the quarterly maximum matter. This is a rewards-card choice, not a guarantee of approval for a first-time applicant.
Guide fee and rewards checked 2026-10-23. Full card review verified 2026-10-26.

Prime Visa
Existing eligible Prime members
Consider it if you already use an eligible Prime membership and shop at participating merchants. Include any membership cost you would incur specifically for this card in your comparison.
Main tradeoff: No annual card fee does not make Prime membership free. Eligible merchants and booking channels matter; the relevant 5% categories fall to 3% without eligible Prime membership.
Guide fee and rewards checked 2026-10-23. Full card review verified 2026-10-19.
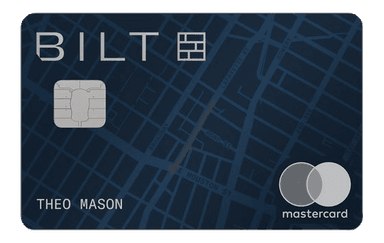
Bilt Blue Card
Housing rewards with spending conditions
Consider Bilt Blue when eligible rent or mortgage payments and the rewards structure fit your household. Housing payments through Bilt have no transaction fee, but the highest points rate is conditional.
Main tradeoff: Choose between Housing-only rewards and Flexible Bilt Cash. Points and Bilt Cash have different uses; neither should be treated as an unrestricted cash-back percentage.
Guide fee and rewards checked 2026-10-23. Full card review verified 2026-10-26.
No annual fee does not mean no fees
Check purchase APR, late-payment and returned-payment charges, balance-transfer and cash-advance fees, and foreign transaction fees. Paying in full can avoid purchase interest when a grace period applies. If you expect to carry a balance, compare financing cost before rewards.
CFPB: credit-card interest and grace periodsCompare flat rewards with capped categories
For illustration, $12,000 of eligible spending at 2% earns $240 before interest or other costs, assuming the earning and payment conditions are met. For Cash+, $2,000 at 5% earns $100 in a quarter; another $1,000 in those capped categories at 1% earns $10. The combined result is $110, not 5% of all $3,000. Use your actual category mix and activation habits.
Check separate membership costs
Prime Visa has no annual card fee, but its higher Amazon, Whole Foods and Chase Travel rewards require eligible Prime membership. If you already pay for Prime for other reasons, that may suit your routine. If joining only for rewards, subtract the membership cost from the extra rewards you expect.
Chase: Prime Visa rewards and membership conditionsUnderstand Bilt’s housing choices
Housing-only rewards use everyday spending relative to housing payments each billing cycle: 25%, 50%, 75% and 100% unlock 0.5x, 0.75x, 1x and 1.25x respectively. Below 25%, a qualifying housing payment earns a 250-point floor per account. Flexible Bilt Cash instead earns 4% Bilt Cash on everyday spending; redeeming $3 unlocks 100 housing points, up to 1x. These choices do not stack. An account in good standing, connected bank account and payment through Bilt are required.
Bilt card offer terms, updated September 18, 2026Check the current Discover calendar
The rotating categories require activation and share a $1,500 quarterly purchase cap. Confirm the current categories and activation timing before spending. A 5% headline does not apply to every purchase, and a first-year promotion is separate from the ongoing earning rate.
Discover: quarterly rewards calendar and capDecide whether an unused card is worth keeping
Keeping a no-annual-fee card can be useful, but it is not always the right choice. Closing a card can raise credit utilization by reducing available credit, while keeping it requires monitoring statements. Consider debt-management needs, account terms and your plans to apply for credit. Avoid a blanket rule to keep every card forever.
CFPB: considerations before closing a credit cardChoose a card you can manage and repay, with rewards you can actually use. A flat-rate option can be easier than maximizing categories. Add membership or housing-based rewards only when their conditions fit your existing habits.
Questions to ask before choosing a card
Does a no-annual-fee credit card cost nothing?
No. It has no annual card fee, but interest and other charges can apply. Separate memberships may also cost money. Read the full fee schedule.
Which option is simplest for everyday cash back?
Citi Double Cash avoids category enrollment and earns its base reward in two parts: when you buy and as you pay. Freedom Unlimited adds higher dining and drugstore rates to a lower base rate. Compare your own spending.
Do 5% cash-back cards earn 5% on everything?
No. Cash+ and Discover use category limits and activation requirements. Prime Visa’s higher rate depends on eligible membership and merchants. Purchases outside those rules earn different rates.
Is Prime Visa a no-annual-fee card without Prime?
There is no annual card fee, but eligible Prime membership is required for the 5% rate at the specified merchants and through Chase Travel. Without it, the relevant rate is 3%.
Does Bilt Blue automatically earn 1.25x on rent?
No. The maximum housing multiplier depends on the selected rewards option and everyday spending. Review the housing-choice explanation above and the current Bilt terms.
Are no-annual-fee rewards cards easy to get?
A $0 annual fee is not an approval standard. Issuers still assess eligibility and creditworthiness. Compare student or secured products if you need a card designed for building credit.
Should I keep an unused no-annual-fee card forever?
Not necessarily. Consider available credit, debt-management needs and the effort to monitor the account. Closing can affect utilization, but that does not make keeping every card the right choice.
Rate this card
Be the first to rate it
Commentson Best No Annual Fee Credit Cards
Comments are stored in your browser during our community preview. Accounts, moderation and cross-device sync arrive with Credit Compound Community.